22Bet · Campaign bonus+250% on your deposit
- Check NZ eligibility
- Read wagering rules
- Confirm withdrawal terms
PRACTICAL GUIDE / NZ
 Partner campaigns: New ZealandUpdated 18 November 2026
Advertisement · 18+. Campaign offer; eligibility and terms apply. A listing is not evidence of New Zealand licensing. We may receive a commission from partner links.
22Bet · Campaign bonus+250% on your deposit
Identify whether a card was renewed, replaced or closed, then ask the issuer and sender how the existing payment will be handled.
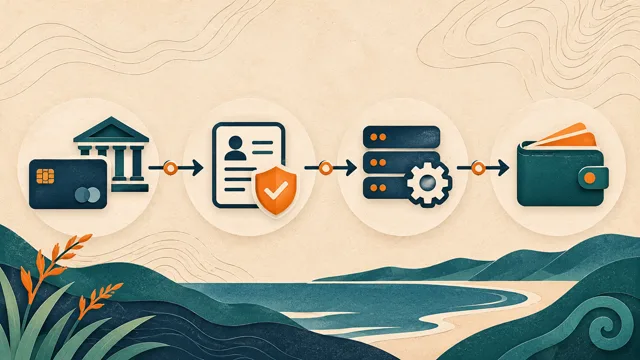
An expired card, a replacement after loss and a closed card account are not the same situation. Start by asking your issuer how the old card relates to the current account. Do not assume that a replacement number means the underlying account has closed, or that an unchanged bank account means every type of incoming card credit will be forwarded automatically. The issuer must explain the treatment that applies to your card and the payment being attempted.
Record when the old card stopped being available and whether the withdrawal was requested before or after that change. Keep only the masked card details needed to distinguish the old and new cards. The payment's amount, currency and request identifier are more useful than circulating a full card number. If replacement followed suspected fraud, maintain the bank's security restrictions while investigating. Restoring a payout route is a separate task from deciding whether an old card should remain blocked.
Find out whether the withdrawal is still awaiting approval, has been sent as a card credit or has been rejected or returned. If it has not been submitted, ask how the provider handles a documented card replacement. If it has already been submitted, obtain the available payment confirmation and ask what tracing information the issuer needs. Changing a saved card in the profile may not alter a payment that is already travelling through a processor.
Do not cancel the request simply because the old card number is displayed. First establish whether the issuer can receive the credit and whether cancellation remains possible. Equally, do not assume that the visible destination is harmless when support cannot explain it. Ask for a written answer linking the old payment method, the current account and the withdrawal request. If a replacement method must be verified, request the exact evidence required and confirmation of how the original request will be treated during that check.
When contacting the issuer, describe an expected incoming card credit rather than an ordinary outgoing purchase. Give the confirmed sending date, amount and currency, and use the tracing details supplied by the sender if they are available. Ask whether the payment has been received, whether it can be applied to the current account, or whether it would be returned. A generic answer about replacing a physical card may not address the incoming payment route.
If the account itself has closed, ask how the issuer handles such credits and what written evidence it can provide. Pass that explanation to the operator through its authenticated support channel. Avoid posting the documents publicly or sharing unrelated banking transactions to prove that the old card existed. If the two institutions give incompatible answers, quote the narrow points of disagreement and ask each to identify the missing fact. Keep their case references so the conversation does not restart from the beginning with every new agent.
If the payment is returned, record the return status and amount before agreeing to a replacement instruction. Ask whether conversion or processing charges affected the returned amount and which party can explain any difference. The original withdrawal should remain traceable in the account history rather than disappearing into a newly created balance without explanation. A replacement request needs its own clear destination and reference.
Use only a route that the provider confirms is legitimate for your account. Do not borrow a relative's card or create another account to bypass payment ownership checks. An instruction to deposit again to unlock an existing withdrawal requires a clear contractual explanation; it is not a normal substitute for tracing the earlier payment. After funds arrive, reconcile the bank record and the operator ledger and save the final response. The useful outcome is a documented return or completed payment, not merely a support message saying that the old card should probably work.
If support requests proof of card replacement, ask the issuer which document confirms that event without revealing sensitive card information. A replacement notice may answer a different question from proof that the underlying account can still receive the expected credit.